You may be reviewing your merchant agreement because you want to switch processors, but an early termination fee could change the cost of leaving. The fee may be a flat amount, a formula tied to the remaining contract term, or part of a larger set of cancellation costs.
Before you cancel, find the signed agreement and calculate the full cost of leaving. Your contract, related equipment or gateway agreements, and applicable law determine which fees may apply.
What a Merchant Services Early Termination Fee Means
An early termination fee (ETF) is a charge a provider may assess when a merchant ends a processing agreement before a stated term expires. The agreement may call it a cancellation fee, account closure fee, early deconversion fee, or liquidated damages. The label alone does not tell you how the amount is calculated or whether it applies to your situation.
The agreement may describe the fee as a fixed cancellation charge or as damages calculated using a stated formula. Do not assume that every fee repays setup costs or represents the provider’s exact lost profit. Read the clause and any definitions it references.
The amount and the process are contract-specific, and applicable law can matter. This article offers general U.S. information, not legal advice. Some state rules apply only to qualifying businesses or agreements. For example, Maryland’s Office of Financial Regulation explains limited rules for certain small businesses and merchant processing agreements; those rules don’t apply to every merchant or contract.
Common Early Termination Fee Structures
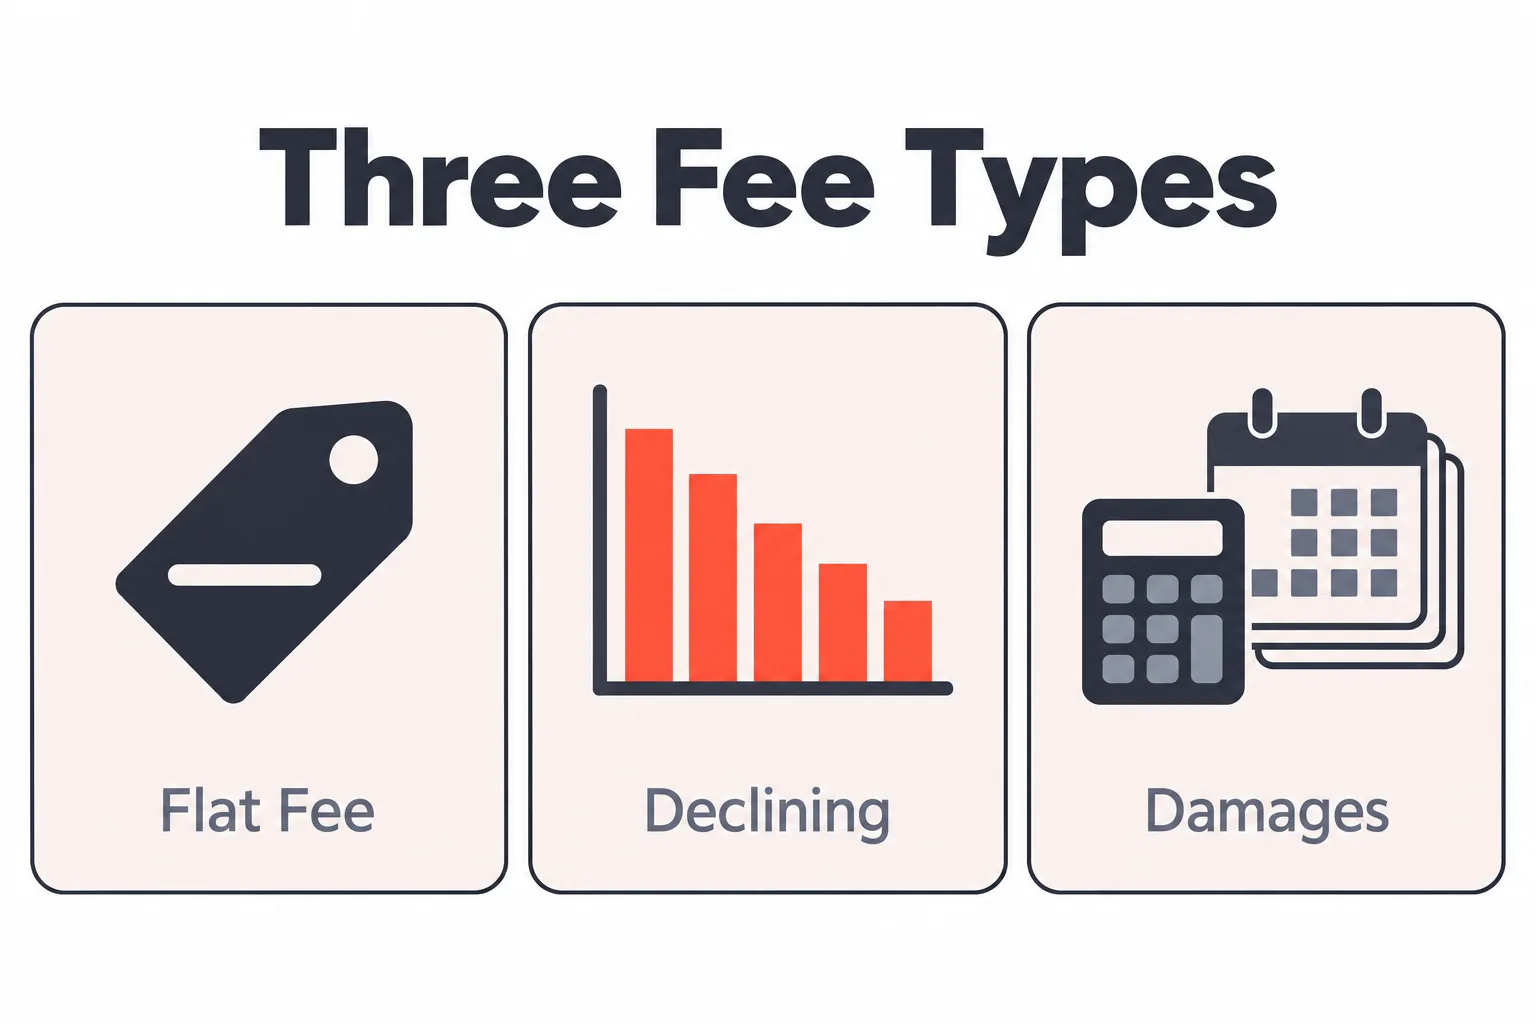
Agreements may use one or more of these structures, or no early termination fee. Check the exact wording and calculation in your own agreement.
Flat Cancellation Fee
A flat fee is a fixed amount stated in the agreement. The amount does not necessarily change based on how many months remain. Do not rely on an online “typical fee” to estimate yours; use the amount and conditions in your contract. You can ask the provider whether it will waive or reduce the fee, but a waiver is not guaranteed.
Prorated or Declining Fee
A declining fee may decrease as you move through the contract term. For example, if the agreement charges $50 for each remaining month and 10 months remain, the formula would produce a $500 fee. This is an illustration only; use the formula in your agreement. Also check whether notice time or a renewal term changes the number of months counted.
Liquidated Damages
A liquidated-damages clause sets an amount or calculation for early termination. Depending on the agreement, the formula may use average monthly fees, a minimum charge, months remaining, or a combination of terms. It may also be combined with a fixed fee or other charges. Do not assume the calculation is simply monthly profit multiplied by the months left.
Look for terms such as “liquidated damages,” “early deconversion,” “monthly minimum,” “average monthly fees,” “remaining term,” or “account closure fee.” Ask for an itemized calculation in writing. If the amount is substantial or the clause is unclear, consider having a qualified attorney review it.
Where to Find Your Actual Exit Cost
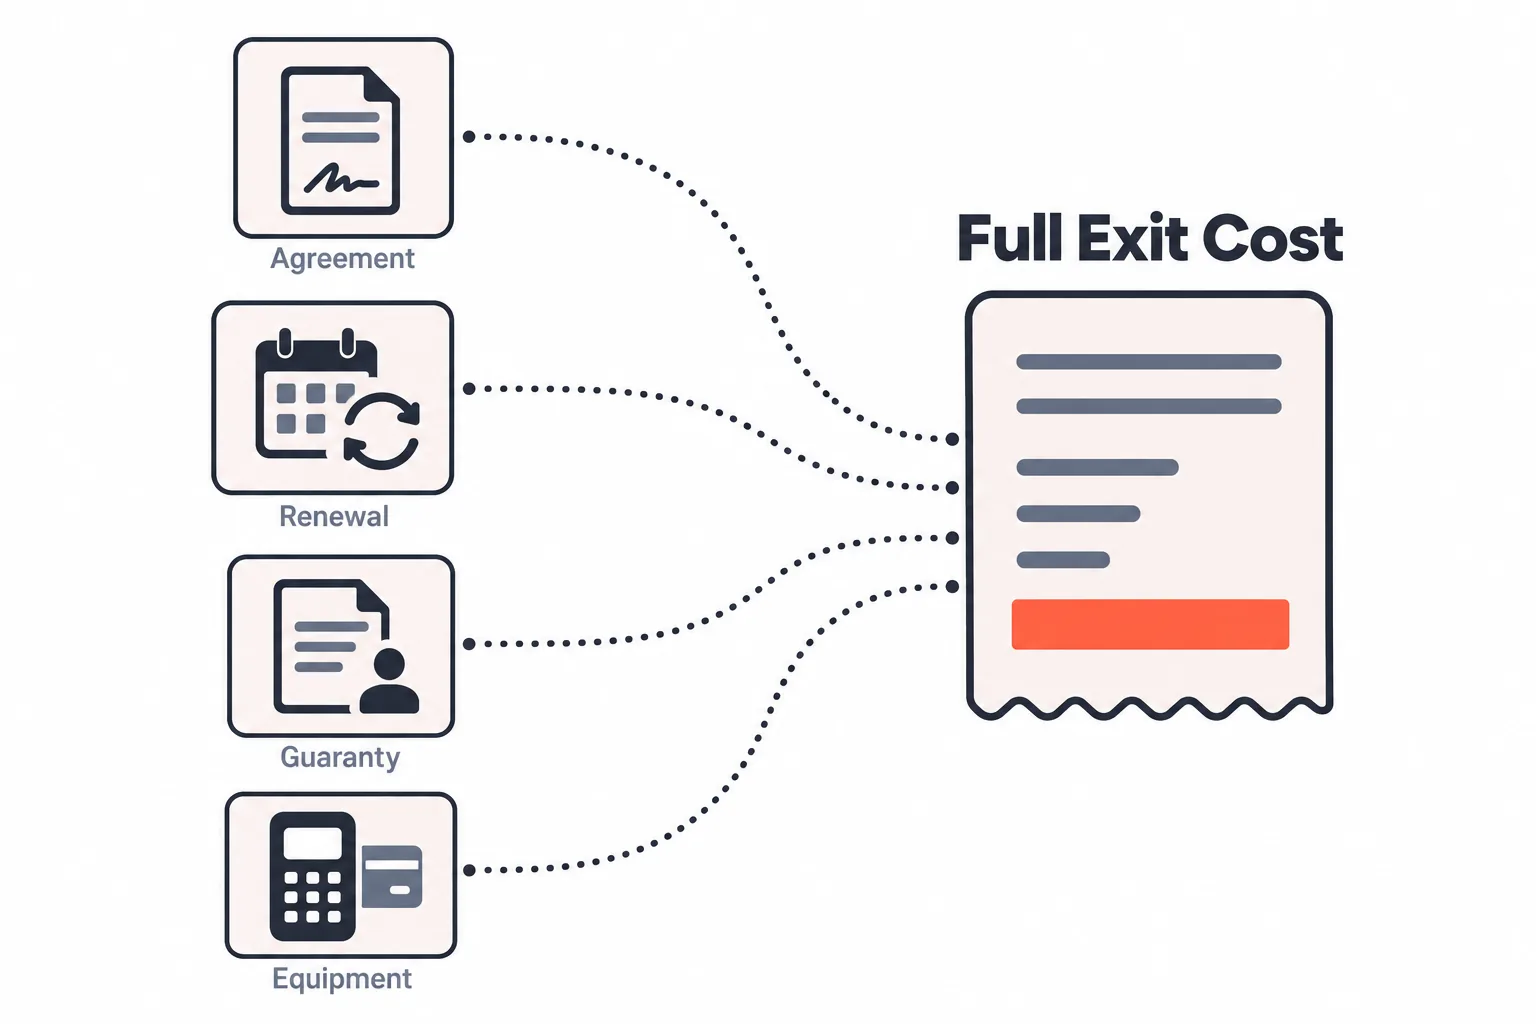
Pull the complete signed agreement, not only the application or pricing sheet. The application may refer to separate terms and conditions, program guides, or other documents. Request a copy of every document the provider says is part of your agreement.
Check the initial term, renewal term, cancellation notice window, required notice method, and fee clause. Some agreements renew automatically unless the provider receives notice by a stated deadline. The length of the renewal and the notice period vary, so record the dates shown in your own contract.
Check for a personal guaranty. If you signed one, it may make you personally responsible for certain obligations of the business, depending on its wording and applicable law. Review the guaranty rather than assuming the business entity alone is responsible.
Look for separate contracts. A gateway, terminal lease, equipment rental, fraud tool, or reporting service may have its own cancellation terms and fees. Closing the processing account may not cancel those agreements.
Ask the provider for the exact fee amount, its calculation, the cancellation procedure, where to send notice, and the effective cancellation date. Check the agreement for how fees may be collected. Keep the answer and your cancellation notice in writing.
The Breakeven Math: Is Paying the Fee Cheaper Than Staying?
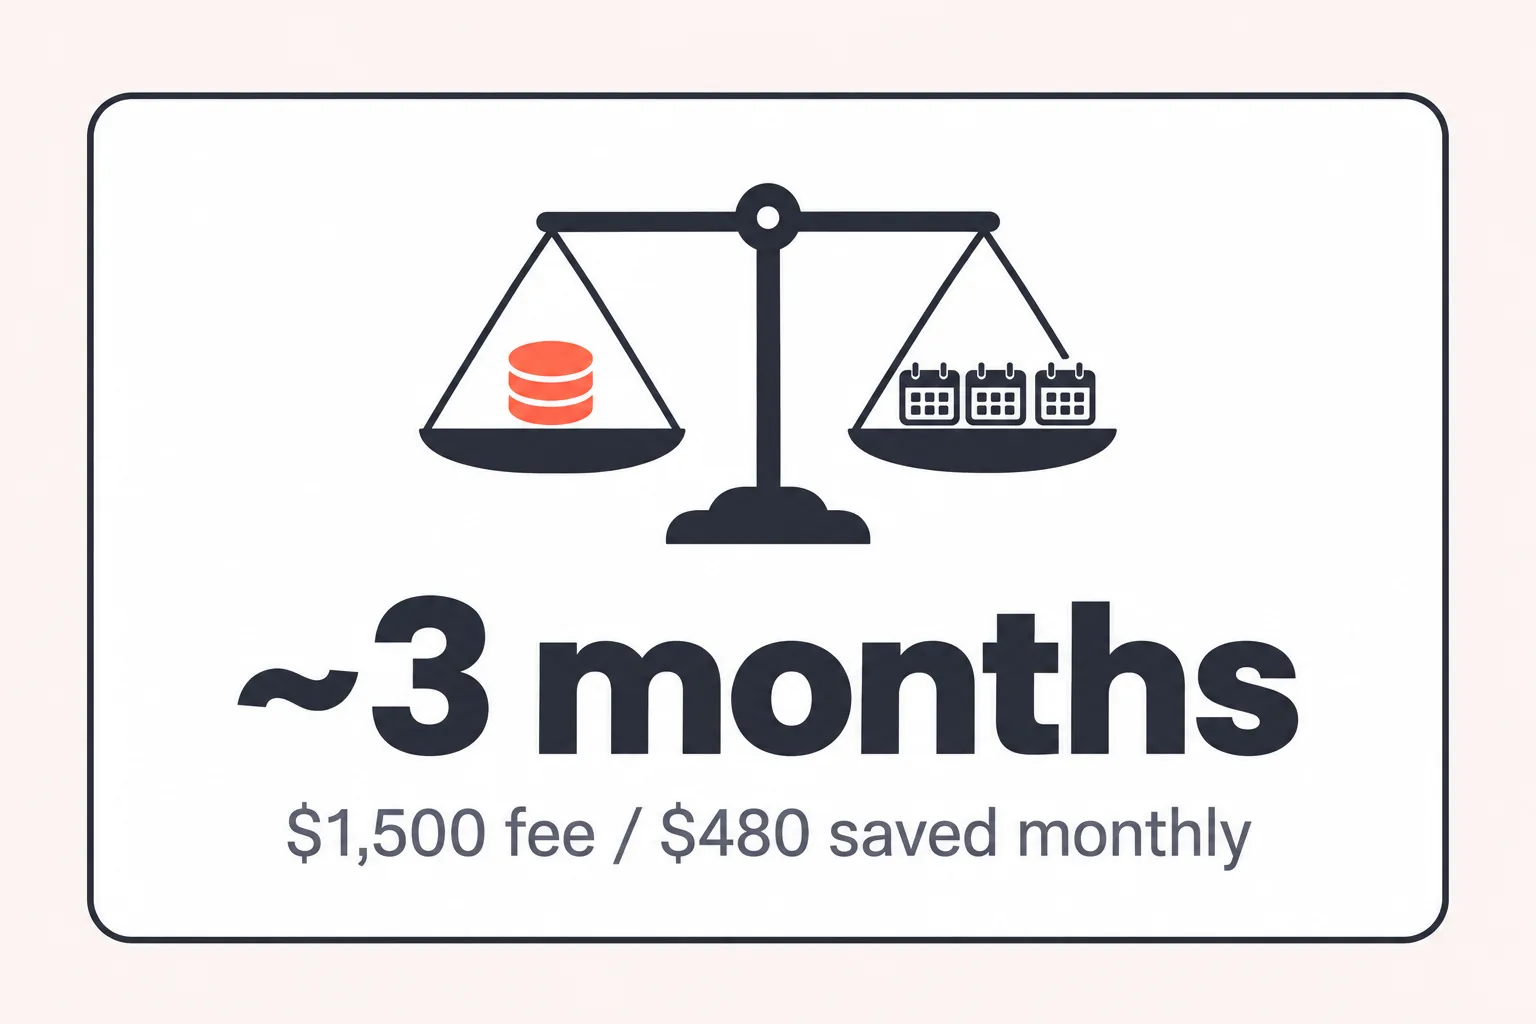
Compare the full cost of staying with the full cost of switching. A lower advertised rate is not enough to make the decision.
Step 1: Calculate your current effective processing cost. Use a recent statement and divide the processing-related fees by the card volume for that period. Include the recurring processing charges that apply to your account, and identify equipment, gateway, or other service costs separately so you can compare like with like.
Step 2: Get a comparable quote. Ask the prospective provider to estimate costs using your actual volume, card mix, transaction sizes, and payment channels. Compare the estimated all-in processing cost, not just a headline rate, with your current costs.
Step 3: Add every cost of leaving. Include the early termination fee, any lease or gateway obligations, notice-period charges, migration expenses, and any other contractual fees. Then compare the total with the savings you expect over the period you plan to use the new provider.
For example, suppose a subscription business processes $80,000 per month and pays $3,600 in processing fees, an effective rate of 4.5%. A hypothetical new quote of 3.9% would be $3,120 per month, a difference of $480. A $1,500 termination fee would take a little over three months of those estimated savings to offset, before migration expenses, equipment, add-on services, reserves, or differences in the quote. These figures are illustrative, not a PPO rate or a prediction of what a provider will offer.
Related readingLowest Credit Card Processing Fees guideRead the guide →Switching may make financial sense when the verified savings outweigh the full exit and migration costs, or when the current setup cannot support your billing needs. Staying may make sense when the contract is close to renewal, the savings are uncertain, or migration would disrupt customer billing. Include account stability and service fit in the decision, not only price.
Reasons to Consider Leaving Besides Price
A rate increase is not the only reason to review a processing relationship. For a subscription business, look at billing continuity, dispute handling, funding interruptions, and whether the provider supports your actual sales model.
Review patterns such as rising reserves, settlement holds, dispute notices, an unclear billing descriptor, or recurring billing rules that do not fit your customer journey. A merchant category code should accurately describe the business; do not change or misstate it to seek different terms.
For recurring payments, make subscription terms and renewal dates clear, use a billing descriptor customers can recognize, and review retry practices so repeated declines do not create unnecessary friction. PPO’s high-risk merchant services describe payment options for higher-risk and recurring-billing businesses. Eligibility and terms depend on the underwriting provider.
Options to Reduce or Avoid the Fee
- Ask the current provider whether it will waive or reduce the fee. Get any approved change in writing and confirm whether other charges still apply.
- Ask a prospective provider whether it offers a transition credit or buyout. Confirm eligibility, amount, timing, and conditions in writing; do not assume this option is available.
- Check whether your agreement allows cancellation without the fee after a rate or term change. Follow the required deadline and notice process. Some changes may be pass-through network or third-party costs and may not qualify under the contract.
- If you believe the provider breached the agreement or charged an undisclosed fee, document the facts and use the contract’s complaint or dispute process. Do not assume that raising a dispute automatically cancels the fee.
- Handle equipment, gateway, and add-on agreements separately. Follow each contract’s return, buyout, or cancellation rules.
- Before sending notice, ask whether your cancellation timing could trigger another month of charges or a renewal. Use the dates and method stated in your agreement.
The FTC’s First American Payment Systems case is an example of action involving alleged hidden terms and surprise exit fees. It concerns that company and does not establish that all processing agreements or fees are the same.
How to Cancel Without Disrupting Customer Billing
1. Confirm the fee calculation, cancellation steps, notice deadline, and effective closure date in writing. 2. Plan recurring billing and any stored-card migration with both providers or gateway support. Do not assume stored credentials can move automatically; ask what secure migration options are supported and what customers may need to do. 3. Coordinate the cutover. Confirm whether overlapping accounts or processing are permitted by each agreement, and test the new setup before moving billing. Do not route transactions through an account in a way that violates its approved use. 4. Ask for separate timelines for final settlements, any reserve, open disputes, and the termination fee. These are different balances and may have different terms. If you accept ACH, confirm settlement and return details with your provider; timing depends on the transaction and applicable rules. 5. Send cancellation notice exactly as the agreement requires and keep proof of delivery and written confirmation. 6. Review statements and bank activity after cancellation for final fees or debits, and contact the provider in writing if something does not match the agreement.
PPO’s online payments describe recurring billing, card-on-file, and multiple merchant-account capabilities under a gateway. Discuss your specific migration and account setup with the provider before changing how transactions are routed.
Early Termination Fees, Reserves, and Final Settlements Are Different
An early termination fee is a contract charge for ending an agreement early. A reserve is funds held under account terms to cover potential liabilities, while final settlements are transactions still being processed or paid out. One does not automatically explain or cancel the others. Ask the provider to list each balance separately, explain its terms, and identify the party responsible for each decision.
PPO says it works with acquiring and processing partners and that merchant funding goes directly from banks to merchants; PPO does not handle merchants’ funds.
The party holding the reserve or settlement balance, not necessarily the sales agent, controls its release under the applicable account terms.
Before Signing the Next Merchant Services Agreement
Ask whether the agreement is month-to-month or fixed-term, what early termination formula applies, and whether there are separate renewal, equipment, gateway, or service obligations. If the provider agrees to waive a fee or change a term, have that commitment included in the signed agreement or a formal amendment.
If your business has multiple brands, channels, or legal entities, ask the provider whether separate accounts are appropriate and disclose how each will be used. Do not split volume to bypass a reserve, closure, or dispute-monitoring decision.
Keep a calendar reminder for renewal and notice dates, and save the signed agreement, pricing schedule, and later amendments where your team can find them.
Frequently asked questions
Can a processor charge a termination fee if I only signed an application?
What if I stop processing and close my bank account?
Is the fee negotiable?
Does closing my business cancel the contract?
How long should I keep the old account open after switching?
Does closing an account put my business on Mastercard MATCH?
Talk It Through Before You Sign or Cancel
If you are setting up card or ACH payments or reviewing a new processing option, contact Premier Payments Online to discuss your business and payment needs. PPO works with acquiring and processing partners; the provider that issued your agreement controls its termination fee, reserve, and account decisions.